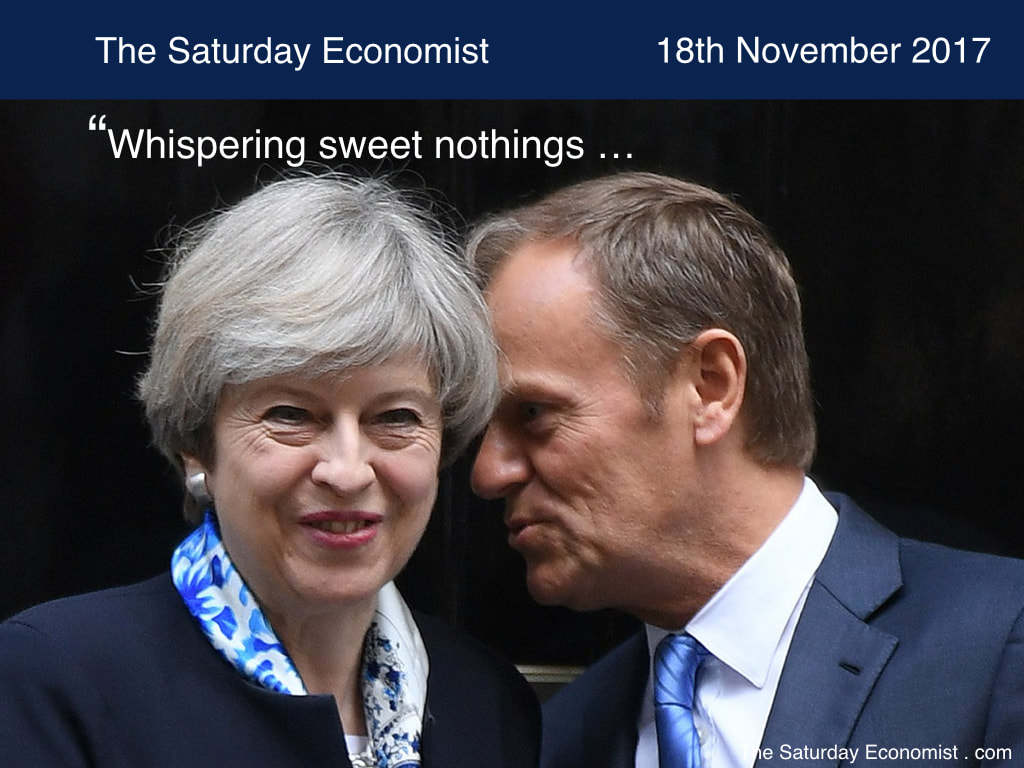
 Whispering sweet nothings ... Donald Tusk asks for more ...
Last week Michel Barnier set the deadline. This week Donald Tusk made it clear. The European Council president has set a deadline of the start of December for Britain to make further movement on the Brexit divorce bill. So far Theresa May has just been whispering sweet nothings. It is time to "up the ante" or "faire monter les enjeux", as they say in Brussels, if progress is to be made in December. Mr Tusk explained, the EU has completed the internal work necessary to give the green light for talks on trade and transition to begin at the next European Council summit in Brussels. But “much more progress” is needed from the UK, on two of the three key issues, in order to break the deadlock. “We will be ready to move on to the second phase in December, but in order to do that, we need to see more progress from the UK side,” said Mr Tusk. Not least the money. More money on the table is required. There can be no talks about trade, until bills have been paid. This has long been clear. David Davis, appears to think, progress and concessions are being made. Tusk took aim at the Brexit secretary. Asked about his claim that Britain had made all the concessions so far in the negotiations, Mr Tusk said: “I can say, only that I appreciate Mr Davis’s English sense of humor.” Ah yes "Sinn für humor" as they say in Frankfurt, "was ist das" they invariably add. The Irish prime minister, Leo Vradkar, warned this week, he could veto Brexit talks over the prospect of a hard border with Ireland. Mr Varadkar, had breakfast with Mrs May at Friday’s summit. He told Sky News: “Before we move to phase two talks on trade, we want taken off the table any suggestion that there will be a physical border or new barriers to trade on the island of Ireland." "After 40 years of marriage, most of them good, now Britain wants a divorce but an open relationship the day after." “Sometimes it doesn’t seem like they have thought all this through.” Well who would think that! Does anyone really know what we would like the open relationship to be? We will have to wait until 11:00pm one day in 2019 to find out. Lloyd Blankfein, boss of Goldman Sachs demonstrated he has a sense of (English) humor. "With so much at stake, and CEOs fretting about the outcome, why not make sure the consensus is still there", he tweeted. Blankfein doesn't tweet much. But yes this is a call for a second referendum. Whispering sweet nothings? Perhaps, but you know it makes sense … Economics news this week ... Inflation and jobs ... Just days to go to the budget. Spreadsheet Phil will reveal the contents of his Red Box on Wednesday. Many believe this will be his last budget. To satisfy the Brexiteers, the Chancellor should ride to the House of Commons in a tumbril, eschewing the Treasury black limo for a much lower estate. Ah yes the tumbril, an open cart tilting backwards to empty out its load. The tumbril was used to convey condemned prisoners to the guillotine during the French Revolution. Such is the current fate of those who do not speak with committed ardour to the cause of decapitating the UK export drive. Johnson and Gove will be knitting and plotting on the front benches on Wednesday. Alas poor Hammond we knew him well. The latest data on inflation, jobs and retail sales were released this week. Inflation CPI basis was unchanged at 3.0% in October. It must have been a close call. Service sector inflation was steady at 2.7%. Goods inflation edged up to 3.3%. RPI inflation increased to 4.0%. Prices are rising but producer price pressures are easing, suggesting the worst may be over in the short term. Just in time for the Bank of England to take the credit. Output prices increased by 2.8%. Input costs increased by just 4.0%, they were up by 20% at the start of the year. The impact of the fall in Sterling and the rise in oil prices, is working its way out of the annualised data. Good new on jobs. The number of people unemployed fell by a further 20,000 in the three months to September to 1.425 million and a rate of 4.3%. The number of vacancies eased back slightly but the data is subject to revision. We don't worry too much about one months information. Good news also on earnings. Earnings increased in September to 2.6% from 2.4% prior month. Household incomes remain under pressure as real earnings fell despite the wage rise. Retail Sales in October fell by -0.3% compared to the same period last year. Spending increased by 2.8% compared to the heady 5% prior quarter. Are consumers "coppering" up for Christmas or Black Friday for that matter? We shall have to wait and see. The figures are concerning but out of context with the jobs and vacancy data for the moment … © 2017 John Ashcroft, Economics, Strategy and Social Media, experience worth sharing. ______________________________________________________________________________________________________________ The material is based upon information which we consider to be reliable but we do not represent that it is accurate or complete and it should not be relied upon as such. We accept no liability for errors, or omissions of opinion or fact. In particular, no reliance should be placed on the comments on trends in financial markets. The receipt of this email should not be construed as the giving of advice relating to finance or investment. ______________________________________________________________________________________________________________ If you do not wish to receive any further Saturday Economist updates, please unsubscribe using the buttons below or drop me an email at [email protected]. If you enjoy the content, why not forward to a friend, they can sign up here ... _______________________________________________________________________________________ For details of our Privacy Policy and our Terms and Conditions check out our main web site. John Ashcroft and Company.com _______________________________________________________________________________________________________________ Copyright © 2017 The Saturday Economist, All rights reserved. You are receiving this email as a member of the Saturday Economist Mailing List or the Dimensions of Strategy List. You may have joined the list from Linkedin, Facebook Google+ or one of the related web sites. Our mailing address is: The Saturday Economist, Tower 12, Spinningfields, Manchester, M3 3BZ, United Kingdom.
0 Comments
Leave a Reply. |
The Saturday EconomistAuthorJohn Ashcroft publishes the Saturday Economist. Join the mailing list for updates on the UK and World Economy. Archives
November 2026
Categories
All
|
| The Saturday Economist |
 RSS Feed
