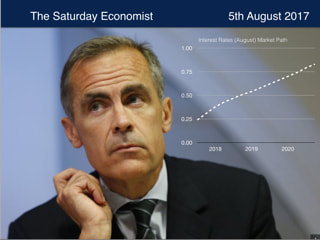
 The Bank of England MPC voted 6 - 2 to keep rates on hold this week. The Committee voted unanimously to maintain the stock of UK government bond purchases at £435 billion. The Committee also voted unanimously to maintain the stock of corporate bond purchases at £10 billion.
In the August Inflation Report, the Bank downgraded forecasts for growth to 1.7% this year and 1.6% next. Concerns about household spending and investment dominate the over view. The "Old Lady" perceives a slow down in investment is materializing. Concerns about life post Brexit in the UK and the lack of a "vision for transition" are a real cause for concern. In the medium term, inflation abates, real incomes are no longer squeezed, the strength of world trade boosts net trade and investment plans return to the board room. The long term growth rate circa 1.75% would be maintained as inflation drifts back to target 2%. So what can we make of the Bank outlook? NIESR released their August forecasts this week. Growth is expected to be 1.7% in the current year rising to 1.9% next. Forecasts for growth, range from 1.1% to 2.1% according to the latest HM Treasury data. A great chance, someone will get it right. Growth in the second quarter was just 1.7% following growth of 2.0% in the first quarter. The Bank appears to have made a fair call for the year in prospect, given the progress year to date. So what of rates? The Governor is hinting at a rate rise. "The Committee judges that some tightening of monetary policy would be required to achieve a sustainable return of inflation to the target. Specifically, if the economy follows a path broadly consistent with the August central projection, then monetary policy could need to be tightened by a somewhat greater extent over the forecast period than the path implied by the yield curve underlying the August projections." Wow! At the moment, markets expect rates to stay on hold until well into next year and to remain sub 1% until 2020. Inflation is expected to peak this year and may have already done so. Strong growth in Europe and the US will create some flexibility for tightening local policy, to the benefit of the Euro and the Dollar. The Bank should take the opportunity to restore rates to 50 basis points at the earliest opportunity. Could it be as early as November ... we shall have to wait and see! ... Should we be worried about personal borrowing ... The Governor appears to be relaxed about personal borrowing despite the concerns raised by the FCA. A mere £1.6 trillion, it's around 80% of GDP after all. Compared to the volume of gilts in issue at £1.9 trillion, of which the central bank holding is £466 billion, perhaps there are other concerns more pressing. The majority of personal debt is secured mortgage lending. The level of unsecured personal borrowing increased in June by 8% to £200 billion. The rate of increase has been at similar levels over the past three years. Debt levels are circa 10% of GDP, compared to 14% of GDP in 2005. In reality, a rate rise is required to cool the expansion of non mortgage lending. For the moment a careful watch is required says the Bank, with some tightening of lending criteria. The Car Market appears to be doing it's best to cool lending and spending according to the latest data from the SMMT. Car sales fell by just over 9% in July. Private and Fleet sales were down in equal measure. Diesel car sales were down by 20%. The SMMT is forecasting a fall in output and registrations for the year as a whole. Investment in car manufacturing fell to £322m in the first half of 2017. This compares with £1.7bn in 2016 and £2.5bn in 2015. The industry is worried about life post Brexit and with good reason. The monthly PMI Markit surveys were released this week. Manufacturing was up, construction was down and service sector growth was steady. A curious curate's egg performance in line with the performance in the second quarter GDP(O). Manufacturing was boosted by export order books, construction was hampered by a commercial sector slowdown. For the year as a whole we expect manufacturing and construction output to rise by around 1.4%. The service sector continues to offer growth of around 2.3% delivering growth of around 1.8% for the economy overall ... Don't Miss the Economics Conference on the 13th October. Our theme is the Economics of Greater Manchester. We will be talking about the Inclusive Growth Challenge, Balancing the Books and the Sectors Driving Growth in the City Region! Another Great Conference in the pro-manchester series ... Book Now Don't Miss Out ... John That's all for this week. Have a great week-end ... If you enjoy the Saturday Economist, why not Join the Club. Now in its sixth year we have produced over 300 updates over the years. Each month we spend over £1,000 on data and subscriptions to maintain the quality of our research. Sign Up and we offer additional information, questions, updates and special deals on our conference programme. © 2017 John Ashcroft, Economics, Strategy and Social Media, experience worth sharing. ______________________________________________________________________________________________________________ The material is based upon information which we consider to be reliable but we do not represent that it is accurate or complete and it should not be relied upon as such. We accept no liability for errors, or omissions of opinion or fact. In particular, no reliance should be placed on the comments on trends in financial markets. The receipt of this email should not be construed as the giving of advice relating to finance or investment. ______________________________________________________________________________________________________________ If you do not wish to receive any further Saturday Economist updates, please unsubscribe using the buttons below or drop me an email at [email protected]. If you enjoy the content, why not forward to a friend, they can sign up here ... _______________________________________________________________________________________ For details of our Privacy Policy and our Terms and Conditions check out our main web site. John Ashcroft and Company.com _______________________________________________________________________________________________________________ Copyright © 2017 The Saturday Economist, All rights reserved. You are receiving this email as a member of the Saturday Economist Mailing List or the Dimensions of Strategy List. You may have joined the list from Linkedin, Facebook Google+ or one of the related web sites. Our mailing address is: The Saturday Economist, Tower 12, Spinningfields, Manchester, M3 3BZ, United Kingdom.
0 Comments
Leave a Reply. |
The Saturday EconomistAuthorJohn Ashcroft publishes the Saturday Economist. Join the mailing list for updates on the UK and World Economy. Archives
November 2026
Categories
All
|
| The Saturday Economist |
 RSS Feed
