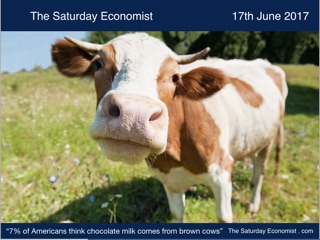
 In the U.S.A. seven percent of Americans think chocolate milk comes from brown cows. Yep, according to a survey from the U.S. Dairy Innovation Center, 16.4 million, misinformed, milk-drinking people, the equivalent of the population of Pennsylvania, just don't accept the inclusion of cocoa and sugar in their basic health drink! Should we be shocked? Not really!
In the U.K. five out of eight members of the Bank of England Monetary Policy Committee think interest rates should be at 0.25%, even though inflation (RPI) hit 3.7% in May. Just three members of the MPC voted to hike rates this week, despite the fact RPI inflation hit 3.7% and the RPIX measure excluding housing costs hit 3.9%. In the U.S inflation slipped back to 1.9% in May from 2.2% in April. The Fed hiked rates despite the fall. More U.S. rate rises are expected this year, with bond sales expected as the QE experiment ends. The Fed intends to increase rates, even though inflation is likely to be around or even below the long term 2% target. In the U.K. headline CPI inflation hit 2.9%. Goods inflation increased to 2.9% from 2.5% last month. Inflation is spiking much earlier than the Bank expected. Manufacturing prices steadied in the month at 3.6%. Evidence of price pressures receding were inherent in the input cost fall from 20% at the start of the year, to 12% in May. "I see just blips" the likely verdict from the Governor, as the decline in Sterling and the fall in oil prices works out of the inflation rate. So what happened in the economy this week ... In the U.S despite the fall in inflation, the Fed is focusing on the strength of the jobs market and the steady growth in the economy. Most analysts expect the US to grow by just over 2% this year as employment continues to rise and wage growth is muted. In the UK, unemployment fell to just over 1.5 million at a rate of 4.6%. The levels are lower than before the great recession. Vacancies fell slightly but may be subject to upward revision. The economy is near full employment with base rates on the floor. The Bank is reliant on the weakness of earnings to justify the accommodating policy stance on rates. Earnings growth slowed to 2.1% in April from 2.3% at the end of March. Construction earnings apparently fell in the month, having risen by over 6% in the final quarter of last year. There is something amiss in the data set. Chocolate milk from brown cows seems more plausible, than the latest batch of earnings data from the O.N.S. For lovers of gloom, retail sales (volume) growth slumped to just 0.9% in May. Household goods stores were hit by a 6% fall in sales. Real earnings are under pressure. The income impact of slowing earnings and rising inflation was a fall of 0.6% in real incomes in April. It won't be much better in May. The good news, retail sales spending increased by 4% in the month, as money still left household pockets. Online sales increased by 15%. The outlook for the rest of the year is uncertain given the political turmoil and the start of the Brexit negotiations next week. The week in markets ... The Dow rallied, the FTSE fell. The Dollar softened against the Euro and Sterling despite the hike in rates. Amazon made the move on Whole Foods for $14 billion dollars. Supermarket shares took a hit. The Empires of the Cloud don't take prisoners ... John That's all for this week. Our Economic Forecasts for June have now been updated. © 2017 John Ashcroft, Economics, Strategy and Social Media, experience worth sharing. ______________________________________________________________________________________________________________ The material is based upon information which we consider to be reliable but we do not represent that it is accurate or complete and it should not be relied upon as such. We accept no liability for errors, or omissions of opinion or fact. In particular, no reliance should be placed on the comments on trends in financial markets. The receipt of this email should not be construed as the giving of advice relating to finance or investment.. ______________________________________________________________________________________________________________ If you do not wish to receive any further Saturday Economist updates, please unsubscribe using the buttons below or drop me an email at [email protected]. If you enjoy the content, why not forward to a friend, they can sign up here ... _______________________________________________________________________________________ For details of our Privacy Policy and our Terms and Conditions check out our main web site. John Ashcroft and Company.com _______________________________________________________________________________________________________________ Copyright © 2017 The Saturday Economist, All rights reserved. You are receiving this email as a member of the Saturday Economist Mailing List. You may have joined the list from Linkedin, Facebook Google+ or one of the related web sites. Our mailing address is: The Saturday Economist, Tower 12, Spinningfields, Manchester, M3 3BZ, United Kingdom.
0 Comments
Leave a Reply. |
The Saturday EconomistAuthorJohn Ashcroft publishes the Saturday Economist. Join the mailing list for updates on the UK and World Economy. Archives
November 2026
Categories
All
|
| The Saturday Economist |
 RSS Feed
